This month, India witnessed a major political landmark, with the Bharatiya Janata Party (BJP), which leads the national government, forming the government in West Bengal for the first time. The state had long been dominated by the Left and, more recently, by the Trinamool Congress. The BJP’s decisive majority in the 294-seat Assembly marks a dramatic shift in one of India’s most politically contested border states.
This is not only a state election story. It sits at the intersection of demography, national security, border management and long-term economic strategy. For global investors watching India, particularly the NRI community, the deeper question is not electoral arithmetic alone. It is whether India is entering a new phase where economic growth is increasingly linked to territorial control, internal stability and demographic management.
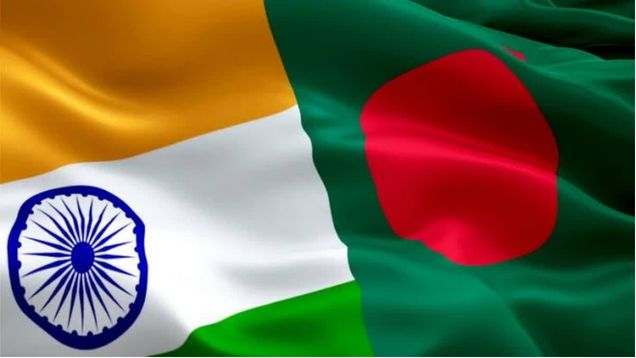
The India-Bangladesh border has historically remained one of the most porous and politically sensitive frontiers in South Asia. Migration, informal trade networks, undocumented labour flows and cross-border political influence have shaped Bengal’s politics for decades. What has changed in recent years is that the Indian state now views border governance not merely as a security issue but as a foundational economic issue. This shift is significant.
Modern economies depend on predictability. Capital flows towards environments where the state can maintain social order, secure infrastructure, regulate labour markets and prevent demographic volatility from becoming political instability.
From the perspective of New Delhi, unchecked infiltration is no longer viewed simply through the lens of identity politics. It is increasingly framed as a challenge to welfare distribution, land economics, urban planning, internal security and electoral coherence.
The implications of this thinking are long term. First, India is moving toward a more security-linked development framework. Border states are likely to see increased spending on surveillance infrastructure, logistics corridors, fencing, digitised identity systems and military-adjacent technologies.
This creates investment opportunities across defence manufacturing, AI-driven monitoring systems, data infrastructure and transport networks. For investors, this resembles a broader global pattern where geopolitical uncertainty is accelerating state-led capital expenditure.
Second, tighter border management could alter labour economics in eastern India. Informal labour inflows historically suppressed wage structures in several sectors including construction, small manufacturing and domestic work. Greater enforcement could gradually formalise labour markets and increase pressure for automation and productivity-led growth. While this may raise short-term costs, it could improve long-term efficiency and tax compliance.
Third, the political centrality of Bengal reflects a larger doctrine emerging within India: economic growth requires insulation from destabilising forces. Investors should understand that the Indian state increasingly sees national security and economic resilience as inseparable.
There are, however, complexities. Aggressive border politics can also create diplomatic friction with neighbouring countries, intensify domestic polarisation and generate reputational concerns internationally.
Global capital generally prefers stability without social fragmentation. The success of India’s approach will therefore depend on whether enforcement is accompanied by institutional fairness, economic inclusion and diplomatic sophistication. Yet the larger trajectory is clear. India is positioning itself not merely as a high-growth market but as a civilisational state seeking strategic insulation in an unstable world.
In an era marked by fractured supply chains, migration crises and geopolitical realignment, governments across the world are rediscovering the economic value of controlled borders and internal cohesion.
Bengal is becoming one of the frontline theatres where this doctrine is being tested. For NRI investors, the takeaway is not simply political. It is structural. The future Indian growth story may increasingly be shaped by sectors linked to sovereignty, security infrastructure, formalisation and state capacity. Behind the rhetoric of elections lies a deeper economic transition: the belief that stability itself is now a national asset.
TOP WATCH
India’s Gold Clampdown
India’s sharp increase in gold and silver import duties from 6% to 15%, alongside new restrictions on duty-free gold imports, is sending ripples through global bullion markets. Discounts on gold in India have surged to record highs as demand slows and traders reassess flows. What appears to be a domestic policy move is actually tied to a much larger concern: protecting foreign exchange reserves amid rising oil prices and West Asian instability. For global investors, India is signalling a broader transition away from consumption-heavy imports toward strategic capital preservation and economic resilience.
India-EU Trade Alignment
As protectionism rises globally and the US-China rivalry deepens, India’s advancing trade integration with the European Union is emerging as a major geopolitical development. Negotiations around a landmark India-EU trade agreement are increasingly viewed as part of a wider Western effort to diversify supply chains away from China while securing democratic economic partners. For India, this could unlock long-term opportunities in manufacturing, pharmaceuticals, clean energy, technology and exports. For global investors, it signals that India is no longer just a growth market but an increasingly central player in the restructuring of the global economic order.
A New Resource War?
The world is entering a new kind of resource war. Unlike the oil conflicts of the past, today’s battle is over rare earth minerals, semiconductors, lithium, food, water and energy corridors that power AI, electric vehicles and defence systems. The pandemic, the Russian invasion of Ukraine and rising tensions between the United States and China have pushed governments to treat economic security as national security. Countries are now racing to secure supply chains, build strategic reserves and reduce dependence on rivals. The next decade may be defined not just by technology leadership, but by who controls the resources behind it.